A small business may have loyal customers, growing sales, and promising opportunities for expansion. Yet when the owner applies for a business loan, the lender needs more than a verbal explanation of how well the company is performing. The lender needs reliable financial evidence showing how money enters the business, how expenses are managed, and whether the company can reasonably repay its debt.
Forming a Limited Liability Company (LLC) can help establish a formal business identity around which owners can build organized financial records. When combined with dedicated business banking and consistent bookkeeping, that structure can make it easier to document revenue and prepare for financing discussions.
1. Create a Clear Financial Identity
An LLC provides a formal legal business structure that can conduct transactions and maintain records under the company’s name.
By opening a dedicated business bank account and directing business revenue through it, owners can create a clearer record of customer payments, operating expenses, supplier transactions, and other financial activity.
This separation can help distinguish business performance from personal transactions and make it easier to assemble documentation when a lender requests financial information.
An LLC alone, however, does not prove that a business generates revenue. The underlying transactions and supporting records matter most.
2. Use Financial Documents to Tell Your Business’s Story
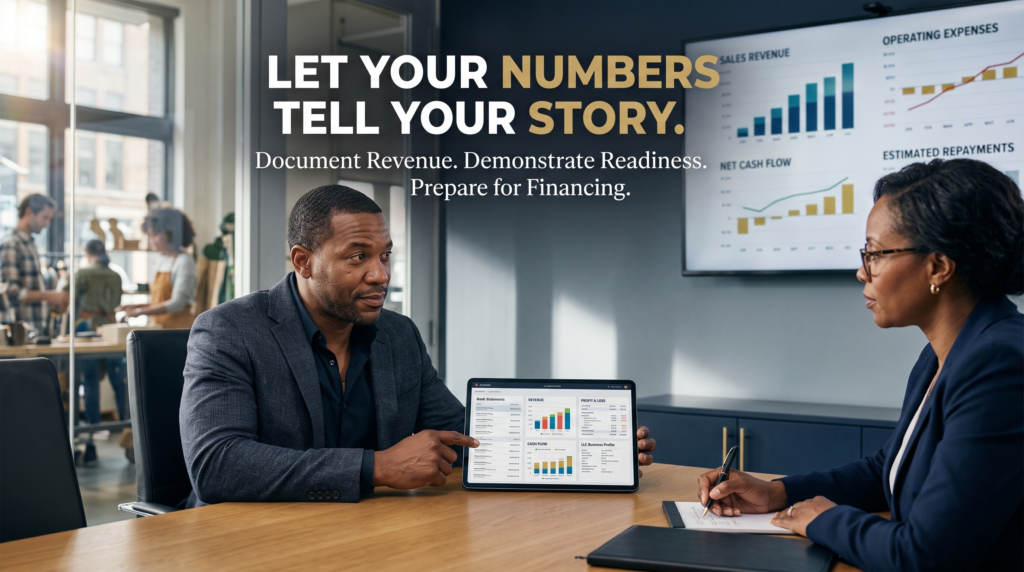
Lenders may request several types of documentation to evaluate a business’s financial condition, including:
- Business bank statements: Show deposits, withdrawals, account balances, and cash movement.
- Profit-and-loss statements: Summarize revenue, expenses, and profit over a specified period.
- Balance sheets: Show business assets, liabilities, and equity at a particular point in time.
- Tax returns: May help verify reported income and assess financial history.
- Accounts receivable reports: Identify customer invoices that have not yet been paid.
- Sales records and contracts: Can provide additional evidence of customer activity and expected payments.
Requirements vary by lender, financing product, loan amount, and business circumstances. Keeping these records current can help owners respond more efficiently when opportunities arise.
3. Demonstrate Consistent Revenue and Cash Flow
Revenue is important, but it is not the same as profit or available cash.
For example, a service-based LLC might generate $15,000 in monthly sales but spend $11,000 on payroll, software, contractors, rent, and other operating costs. The business must also account for taxes, existing debt payments, and the timing of customer collections.
A lender may therefore evaluate not only sales volume but also expenses, profitability, cash-flow consistency, existing obligations, and the company’s capacity to repay the proposed financing.
Business owners should review these figures before applying and understand how a new monthly payment would affect operations.
4. Connect Revenue Documentation to Business Credit
A well-documented financial history may support a broader business credit strategy. Owners can maintain consistent business information, pay eligible credit obligations on time, monitor commercial credit reports, and avoid taking on debt the business cannot comfortably manage.
However, revenue records do not automatically establish a business credit score or guarantee financing. Some lenders also consider the owner’s personal credit, collateral, time in business, personal guarantees, and other factors.
5. Prepare Before You Need the Money
Businesses often seek financing when they need to purchase inventory, hire employees, acquire equipment, invest in marketing, or fulfill a larger customer contract.
Preparing financial statements and cash-flow forecasts in advance can help an LLC identify how much capital it needs and explain how the funds will be used.
The bottom line: An LLC can provide a formal framework for maintaining business financial records, but lenders ultimately assess the company’s financial evidence and ability to repay. Organized records, realistic forecasts, and responsible financial management can help make that assessment clearer.