Every small business faces risks. A customer could claim that a service caused financial damage, a visitor could suffer an injury on business premises, equipment could be stolen, or a cyberattack could interrupt operations. Without preparation, an unexpected incident can lead to significant expenses, lost revenue, and potentially serious financial consequences.
A Limited Liability Company (LLC) can help establish a legal separation between a business and its owners. Business insurance provides another layer of protection by covering certain losses and liabilities, depending on the policy. Together, they can form important components of a small business risk-management strategy.
1. Understand What an LLC Can—and Cannot—Protect
An LLC generally helps separate business liabilities from an owner’s personal assets. If the company faces a lawsuit or unpaid business obligation, the owner’s personal assets may receive protection under applicable law.
However, that protection is not absolute. Personal guarantees, certain personal acts of negligence, fraud, some tax liabilities, and circumstances in which a court disregards the LLC’s separate existence can expose an owner to personal liability.
Maintaining separate business accounts, accurate records, proper contracts, and appropriate operating procedures helps reinforce the distinction between the owner and the business.
2. Use Insurance to Address Risks an LLC Does Not Eliminate
An LLC is not an insurance policy. It does not pay covered claims, replace damaged equipment, or automatically compensate a business for lost income.
Depending on the company’s activities, useful policies to evaluate may include:
- General liability insurance: May cover certain third-party bodily injury, property damage, and related claims.
- Professional liability insurance: May help cover eligible claims alleging professional errors, negligence, or failures in providing services.
- Commercial property insurance: May cover specified damage to insured business property.
- Cyber insurance: May help address covered cyber incidents, data breaches, and certain recovery expenses.
- Workers’ compensation insurance: May cover eligible workplace injuries and is required for many employers under applicable laws.
- Business interruption coverage: May help replace certain lost income when a covered event disrupts operations, subject to policy terms.
Not every business needs every policy. Coverage, exclusions, deductibles, limits, and legal requirements should be reviewed with a qualified insurance professional.
3. Strengthen Customer Confidence and Win Opportunities
Insurance can also support business development. Commercial customers, property managers, and government contractors may require vendors to carry specific coverage before awarding a contract.
For example, a small web development company pursuing a corporate project may be asked to provide proof of professional liability or cyber coverage. A cleaning business seeking commercial contracts may need general liability insurance and other required coverage.
An LLC can provide the formal business structure for entering agreements, while appropriate insurance may help satisfy customer requirements and demonstrate that the company takes risk management seriously.
4. Protect Cash Flow and Business Continuity
Unexpected claims can consume money intended for payroll, inventory, marketing, or expansion. Appropriate insurance may help reduce the financial impact of covered incidents, allowing a business to preserve working capital.
Business owners should review potential risks regularly, maintain emergency reserves, and understand how deductibles and coverage limits affect their ability to absorb losses.
5. Build a Stronger Foundation for Long-Term Growth
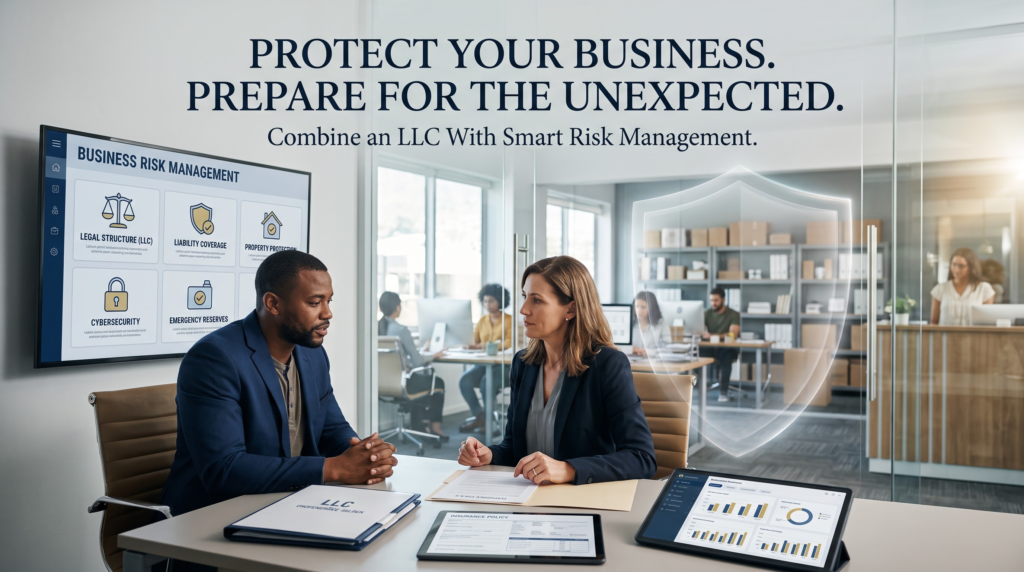
Responsible risk management can help a business operate with greater confidence. An LLC, suitable insurance, written contracts, sound cybersecurity practices, and reliable financial records work together to create a more resilient operation.
The bottom line: An LLC can provide a legal foundation for separating business and personal liabilities, while business insurance can help address specific covered risks. Neither guarantees complete protection, but combining them thoughtfully can help small businesses manage uncertainty, maintain customer trust, and pursue growth more responsibly.